FICO's hold on mortgage credit scores just opened to competition. Whether the new score is equal is still being tested.
Joe, founder of FinBizify
·
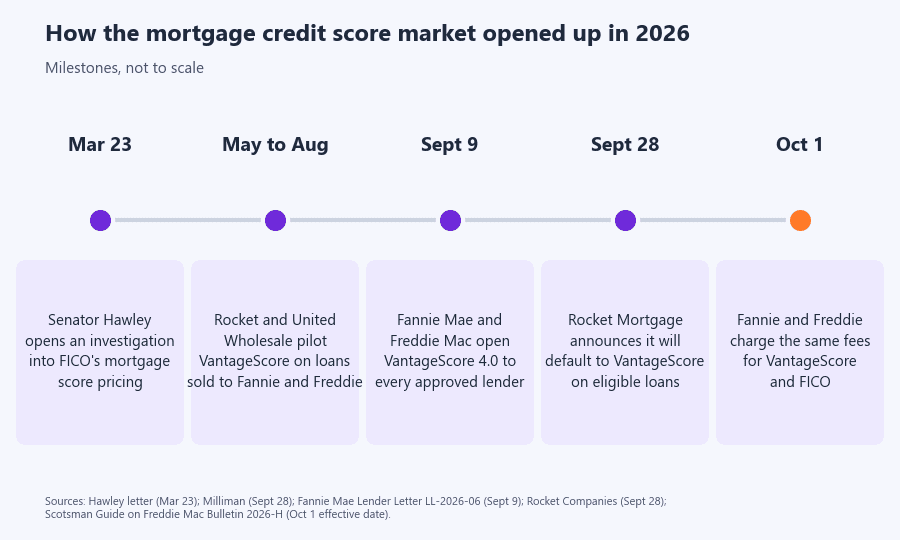
On September 9, 2026, Fannie Mae and Freddie Mac, the two government-sponsored companies that buy home loans from mortgage lenders, began letting every approved lender use VantageScore, a newer credit score offered by the three credit bureaus Experian, Equifax, and TransUnion, to decide who qualifies for a mortgage.[1] Until this fall, FICO was the only credit score the two companies accepted on the mortgage loans they buy from lenders.[2] Because Fannie and Freddie back majority of the U.S. mortgage market, the score they accept shapes the score nearly everyone applying for a home loan gets judged by.[3]
How one company ended up with the market
A credit score is a number, usually between 300 and 850, that a lender uses to judge whether a borrower will repay. FICO charges a fee, called a royalty, each time a lender buys one of its credit scores, and that fee is often passed on to the borrower. A mortgage application needs three FICO scores, one from each of the three credit bureaus (Experian, Equifax, and TransUnion), so the fee is charged three times per application.[2]
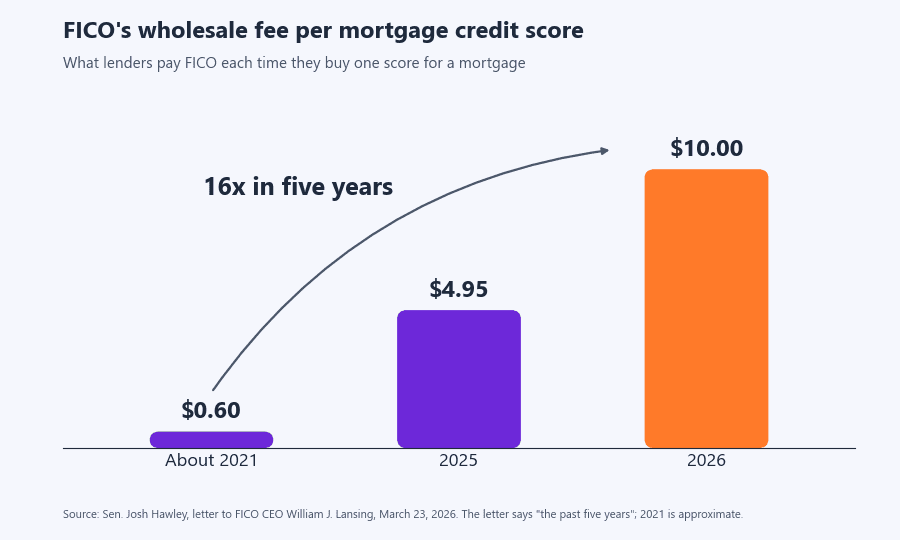
Here is what happened to that fee. A March 23, 2026 letter from Senator Josh Hawley to FICO's chief executive says the royalty on mortgage scores rose from $0.60 to $10.00 over five years, a 16x increase, and that FICO's scores are used by 90% of lenders.[2] Hawley is investigating whether those increases reflect monopoly pricing. The letter notes that FICO has argued the royalty is a small share of overall closing costs.[2]
What changed
VantageScore is made by the same three credit bureaus, who also sell FICO scores and pay FICO a royalty on them.[4] Consumers often see VantageScore in free credit-score apps, but lenders selling these mortgages could not use it.
In September, the Federal Housing Finance Agency, which oversees Fannie and Freddie, directed them to approve all lenders for VantageScore, and both companies updated their lender rules on September 9.[1][3] For loans settled starting October 1, 2026, the two companies charge the same fees no matter which score is used.[5] Before that, they treated VantageScore as the score that runs higher for the same borrower, so they marked it down before setting fees.[6]
Are the two scores equal?
Not yet, and the evidence so far points both ways. The two scores use different formulas and different data, so one person can have two different numbers.
The two biggest home lenders, Rocket Mortgage and United Wholesale Mortgage, together made about one in eight U.S. home loans in 2025.[7] Rocket tested both scores on 1.4 million credit reports this year and says VantageScore 4.0 averaged 11 to 12 points higher than the older FICO model.[3][8] A Rocket executive says most borrowers got the same price or a slightly better one with VantageScore.[3] For the borrowers whose price improved, the savings averaged $1,600 at closing, according to Rocket, which does not say how many borrowers that covers.[8] United Wholesale plans to pull both scores and use whichever is higher.[3][8]
Investors who buy these loans may see it differently. Milliman studied 118,618 Fannie Mae and Freddie Mac loans made by Rocket and United Wholesale between May and August 2026. Loans scored with VantageScore carried interest rates about 0.09% higher on average than comparable loans scored with FICO. For illustration, that is the gap between a 6.00% rate and a 6.09% rate. The gap shrank from 0.12% in May to 0.05% in August, and Milliman cautions that the sample is two lenders in a test period.[6] Whether a higher number carries the same repayment risk is still unanswered.
Why it matters to what teens learn
A credit-score lesson written a year ago describes a mortgage world with one score. "Lenders usually pull a FICO Score" is still true for most lenders today, but VantageScore went from essentially zero to roughly 3% of the loans Fannie and Freddie packaged into securities in the six months through September, so the statement now has an expiration date measured in quarters.[3]
Teens and young adults adopt new tools and trends early. They need education that explains what is shaping their money now, and a lesson written for last decade's market leaves them behind it. An earlier note made the same point about paper checks, and a royalty hidden inside a loan echoes the fee plumbing behind free stock trades.
FinBizify's Investor lesson on credit reports and scores already teaches FICO and VantageScore as two models built by different companies. The annual refresh cycle the lessons run on turns a development like this one into an edit rather than a rewrite.
Sources
"Lender Letter LL-2026-06: VantageScore 4.0 Broad Lender Availability," Fannie Mae, September 9, 2026. https://singlefamily.fanniemae.com/media/document/pdf/lender-letter-ll-2026-06-vantagescore-40-broad-lender-availability
Josh Hawley, letter to William J. Lansing, Chief Executive Officer, Fair Isaac Corporation, March 23, 2026. https://www.hawley.senate.gov/wp-content/uploads/2026/03/2026-03-23-Hawley-Oversight-Letter-to-FICO.pdf
Jasmine Li and AnnaMaria Andriotis, "A Credit-Score Shift at Fannie and Freddie Is Shaking Up the Mortgage Market," The Wall Street Journal, October 12, 2026. https://www.wsj.com/finance/regulation/fannie-freddie-vantagescore-mortgages-85b41d3
"What Is a VantageScore Credit Score?" Experian. https://www.experian.com/blogs/ask-experian/what-is-a-vantagescore-credit-score/ ; Fair Isaac Corporation FY2025 Form 10-K, SEC. https://www.sec.gov/Archives/edgar/data/814547/000081454725000030/fico-20250930.htm
"Fannie and Freddie merge loan-level pricing for VantageScore, FICO credit scores," Scotsman Guide, October 1, 2026 (quoting Freddie Mac Seller/Servicer Guide Bulletin 2026-H). https://www.scotsmanguide.com/news/fannie-and-freddie-merge-loan-level-pricing-for-vantagescore-fico-credit-scores/
Ryan Huff, Jonathan Glowacki, and Ricardo Nunez Magana, "Early indications of mortgage pricing under VantageScore," Milliman, September 28, 2026. https://www.milliman.com/en/insight/early-indications-mortgage-pricing-under-vantagescore
"Rocket leads UWM in 2025 HMDA loan count, trails in volume," American Banker, April 3, 2026 (Rocket Mortgage 429,332 loans, 6.33%, and United Wholesale Mortgage 422,120 loans, 6.25%, of about 6.8 million 2025 originations). https://asreport.americanbanker.com/news/rocket-leads-uwm-in-2025-hmda-loan-count-trails-in-volume
"Rocket Mortgage Becomes First Home Lender to Use VantageScore as its Preferred Scoring Model on All Eligible Loans," Rocket Companies, September 28, 2026. https://www.prnewswire.com/news-releases/rocket-mortgage-becomes-first-home-lender-to-use-vantagescore-as-its-preferred-scoring-model-on-all-eligible-loans-302892051.html
FinBizify is building money education lessons that teenagers actually want to finish, taught through real companies and real dollar amounts.